The Hidden Cost of Buying a Home: What the Seller’s Disclosure Form May Not Tell You
1. The storm that changed everything
Picture this. A young couple finally gets the keys to their first home. The garden is pretty, the kitchen is freshly painted and the transfer went smoothly. Three weeks later, a summer thunderstorm rolls over the Highveld, the kind that arrives with hail and a wall of water. By the next morning there is a brown stain spreading across the lounge ceiling, damp insulation in the roof space and a contractor’s quote that makes their stomachs drop: a significant portion of the roof structure and waterproofing needs repair.
The obvious questions follow quickly. Did the seller know? Should the disclosure form have mentioned it? Will the insurer pay?
This is an illustrative scenario, and it is worth saying plainly: in a situation like this, nobody can assume the seller was at fault. Roofs can fail without anyone having known about a problem, and whether a seller knew of a defect, and whether they hid it, are questions that depend on evidence and, where disputed, are decided by a court. What the scenario does show is how much a buyer stands to lose when the answers are unclear. Understanding your position before you sign is far cheaper than finding out afterwards.
2. What is the mandatory disclosure form?
Since 1 February 2022, the Property Practitioners Act 22 of 2019 has required sellers who use a property practitioner (an estate agent) to complete and sign a mandatory disclosure form. This is set out in section 67 of the Act, with the prescribed format found in the regulations.
In broad terms, section 67 provides that:
- A property practitioner may not accept a mandate to sell a property unless the seller has provided a fully completed and signed disclosure form.
- The practitioner must give a copy of the completed form to a prospective buyer who intends to make an offer.
- The completed form is attached to, and forms part of, the sale agreement.
- If the form is not completed, signed or attached, the agreement is to be interpreted as though no defects were disclosed to the buyer.
The form asks the seller to declare the defects and deficiencies they are aware of, covering matters such as the roof, walls, damp, plumbing, electrical systems, structural issues and municipal or building-plan concerns. Practitioners who ignore the requirement can face regulatory action by the Property Practitioners Regulatory Authority (PPRA).
One important nuance: section 67 is aimed at property practitioners. A purely private sale, with no agent involved, falls outside it, which is another reason buyers in private deals need to be extra careful.
3. What does the form actually guarantee?
Here is where many buyers get a nasty surprise. The disclosure form is not a warranty that the home is free of defects.
The form records what the seller knows and is prepared to declare. It does not record what the seller does not know. A slow leak above a ceiling board, a cracked truss, deteriorating waterproofing under a flat-roof section or an old repair done poorly by a previous owner may be invisible to everyone, including the person who has lived there for years.
Think of the form as a statement of the seller’s knowledge on the day they signed it, not an inspection report and not a guarantee. It is valuable, because a signed, detailed form creates a record and encourages honesty, but it is a starting point for your due diligence, not the end of it.
It is also important to understand what disclosure does not mean. When a seller declares a defect on the form, they are only telling you that they know about it. It is not an acknowledgement that the seller will fix anything, unless the offer to purchase (OTP) expressly says so, for example by making the repair a suspensive condition of the sale. If a repair matters to you, make sure it is written into the agreement before you sign.
4. What does voetstoots mean?
Most South African sale agreements contain a voetstoots clause. Literally “with the foot push”, it means the buyer takes the property as it stands, with its defects, whether visible or hidden. For the seller, it is a powerful protection against claims for defects they genuinely did not know about.
But voetstoots has limits:
- Fraudulent concealment. Under our common law, a seller cannot rely on voetstoots to shelter a defect they knew about and deliberately hid. A buyer who alleges this generally carries the burden of proving that the seller knew of the defect and took steps to conceal it, or deliberately failed to disclose it. That can be a difficult standard to meet.
- The Consumer Protection Act. Where a seller is acting in the ordinary course of business, for example a developer or property dealer selling stock, the Consumer Protection Act 68 of 2008 can limit how far a voetstoots clause protects them. Ordinary private homeowners are generally not covered in the same way.
- The disclosure form does not abolish voetstoots. Section 67 and voetstoots sit side by side. The form puts known defects on the table, while voetstoots continues to allocate the risk of defects nobody knew about.
The practical lesson is that voetstoots is usually the buyer’s risk and the seller’s shield, unless fraud can be proven. Proving fraud after the fact is expensive, slow and uncertain. Prevention is a far better strategy.
5. Why inspections matter
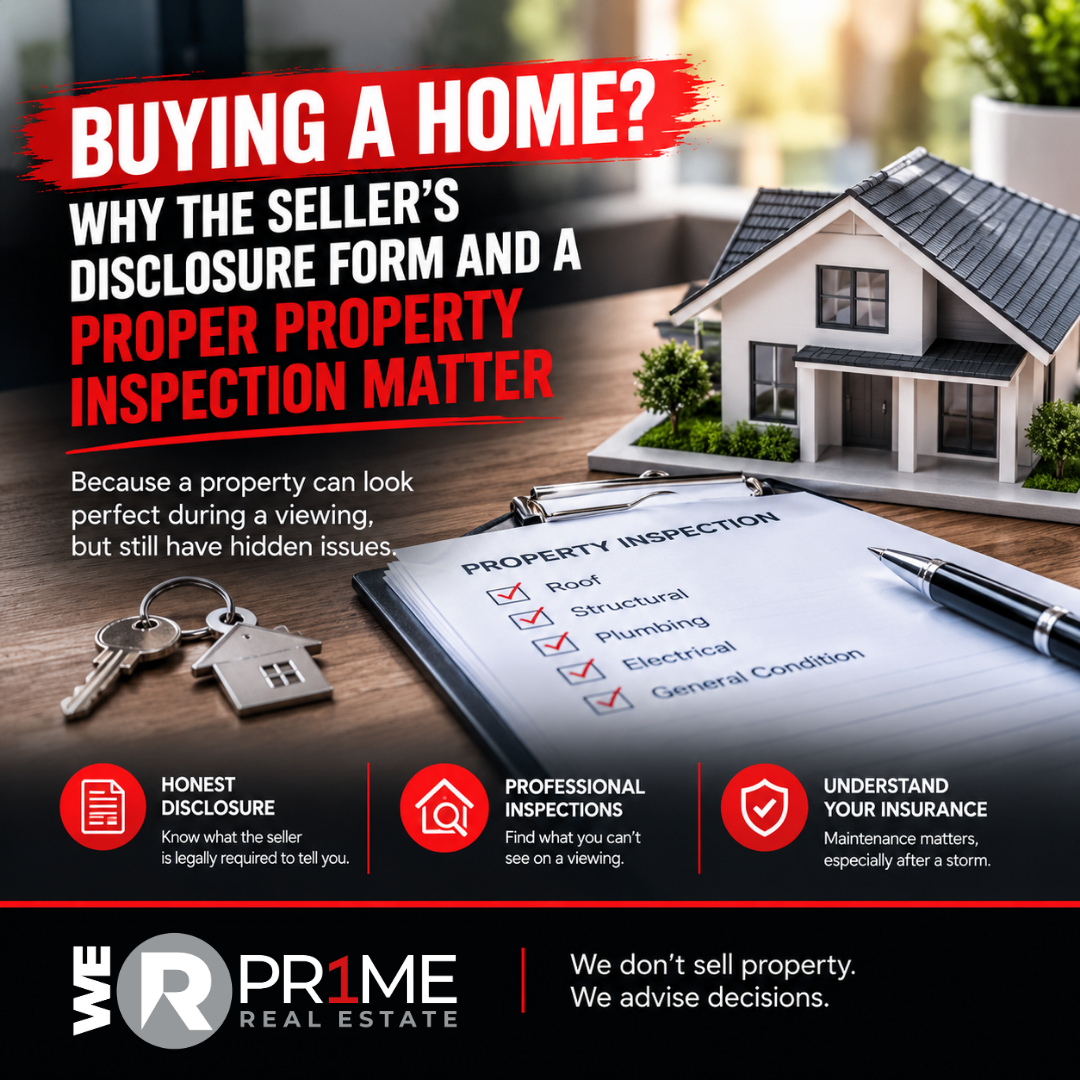
A professional inspection is the most effective way to turn unknown risks into known ones before your money changes hands. The Act itself recognises a buyer’s right to arrange an independent inspection, usually at the buyer’s cost.
For a home that has weathered Highveld storms, Cape winds or coastal salt air, consider:
- A roof inspection by a qualified roofing contractor, covering tiles or sheeting, flashing, gutters, waterproofing, timber condition and, where relevant, the presence of asbestos-cement sheeting.
- A general building or home inspection, which looks at damp, cracks, ceilings and structural signs.
- Specialist reports where appropriate, such as electrical, plumbing, gas, borehole or solar installations, and wood-borer or beetle reports where required.
Crucially, make the inspection part of the contract. Ask your agent and conveyancer to build written inspection conditions into the offer to purchase, such as:
- A clause making the sale subject to satisfactory inspection reports within a stated number of days.
- A right to cancel, or renegotiate the price or repairs, if material defects are found.
- Clear access arrangements for inspectors.
A verbal assurance (“the roof is fine, it’s never leaked”) carries little weight. If it matters, it should be in writing.
6. When insurance and maintenance collide
Many buyers assume that if a storm damages the roof, insurance will simply pay. In practice, it is not always that simple.
Short-term insurance policies commonly cover sudden, accidental events such as a storm, but they typically exclude damage caused by gradual deterioration, wear and tear or lack of maintenance. If an insurer’s assessor concludes that water got in because the roof was already worn, poorly maintained or defective before the storm, a claim may be reduced or declined.
That is where two problems collide. The roof that failed in the storm may have been in poor condition before you bought the home, yet you now carry both the repair bill and a potentially difficult claim.
Sensible steps:
- Read your policy wording for storm, water and maintenance exclusions, and ask your broker to explain them in plain language.
- Arrange cover from the date of transfer, or earlier if you take occupation before then, and confirm any conditions attached.
- Keep your inspection report. A clean roof report before transfer can help show the condition of the property when you took ownership.
- Maintain proactively: clear gutters and downpipes, reseal flashings, and repair loose tiles or sheeting promptly, keeping receipts.
- If a claim is declined, ask for the reasons in writing. Policyholders can escalate disputes through the insurer’s complaints process and, if unresolved, the Ombudsman for Short-term Insurance.
7. A practical checklist for buyers and sellers
For buyers
Before you sign
- Insist on receiving the completed, signed disclosure form before making an offer, and read every line.
- Ask questions about anything marked “unknown”, vague or left blank.
- Visit the property at different times, and after rain if possible. Look for stains, bubbling paint, musty smells and sagging ceilings.
- Commission a roof inspection and a general building inspection.
- Add written inspection conditions and cancellation or renegotiation rights to the offer.
- Ask for compliance certificates (electrical, plumbing, gas, electric fence, beetle where applicable) and confirm that building plans were approved.
- Speak to your insurer or broker about cover and exclusions.
Before transfer
- Do a final walk-through, ideally with your inspector’s report in hand.
- Confirm that agreed repairs were completed properly and obtain invoices and guarantees.
- Make sure insurance is in place before you take occupation.
- Keep copies of every document, including the disclosure form, reports and correspondence.
For sellers
- Complete the disclosure form honestly and thoroughly. When in doubt, disclose.
- Disclose known leaks, past repairs and insurance claims, even if you believe the problem is fixed.
- Consider a pre-sale roof and building inspection. It can build buyer confidence and avoid surprises mid-deal.
- Attach invoices, guarantees and certificates for repairs and installations.
- Fix what you reasonably can, and document what you cannot.
- Remember that a voetstoots clause is not a licence to stay quiet about what you know.
8. The WE R PR1ME perspective
Buying or selling a home is one of the biggest financial decisions most South Africans will make. At WE R PR1ME Real Estate, we believe the best transactions are the ones where everyone understands what they are signing and nobody is surprised afterwards.
Transparency protects everyone. Sellers who disclose fully reduce the risk of disputes, and buyers who inspect and ask questions can make confident decisions and budget properly for what lies ahead. The disclosure form, a professional inspection, a carefully drafted agreement and the right insurance each cover a different part of the picture. None of them works well alone.
If you are thinking of buying or selling, talk to us early. We will help you understand the paperwork, point you towards qualified inspectors, and encourage you to take advice from your conveyancer, attorney and insurer where your situation calls for it.
This article is for general information only and is not legal, financial or insurance advice. Laws, regulations and insurance policy terms differ and can change, and every transaction is different. Always obtain professional advice specific to your circumstances before signing any agreement.